State of the Restaurant Industry 2026
With inflation moderating and labor shortages receding, restaurant operators have reason for optimism, but little margin for error as value-seeking consumers, elevated costs and shifting dining behaviors continue to pressure unit economics.
On this page
Published October 15, 2026 | 10 minute read
Key takeaways:
- Amid growing concerns about affordability, consumers are still spending on dining out, but more selectively.
- Operating expertise is becoming a key competitive differentiator, as operators look for strategies to maintain margins by realizing efficiencies.
- Restaurants are finding ways to adjust to a shift in consumer preferences, driven in part by nutritional trends and the prevalence of GLP-1 medication use.
- The beverage sector is booming as consumers switch to customizable, lower-ticket items that can complement or replace traditional meals.
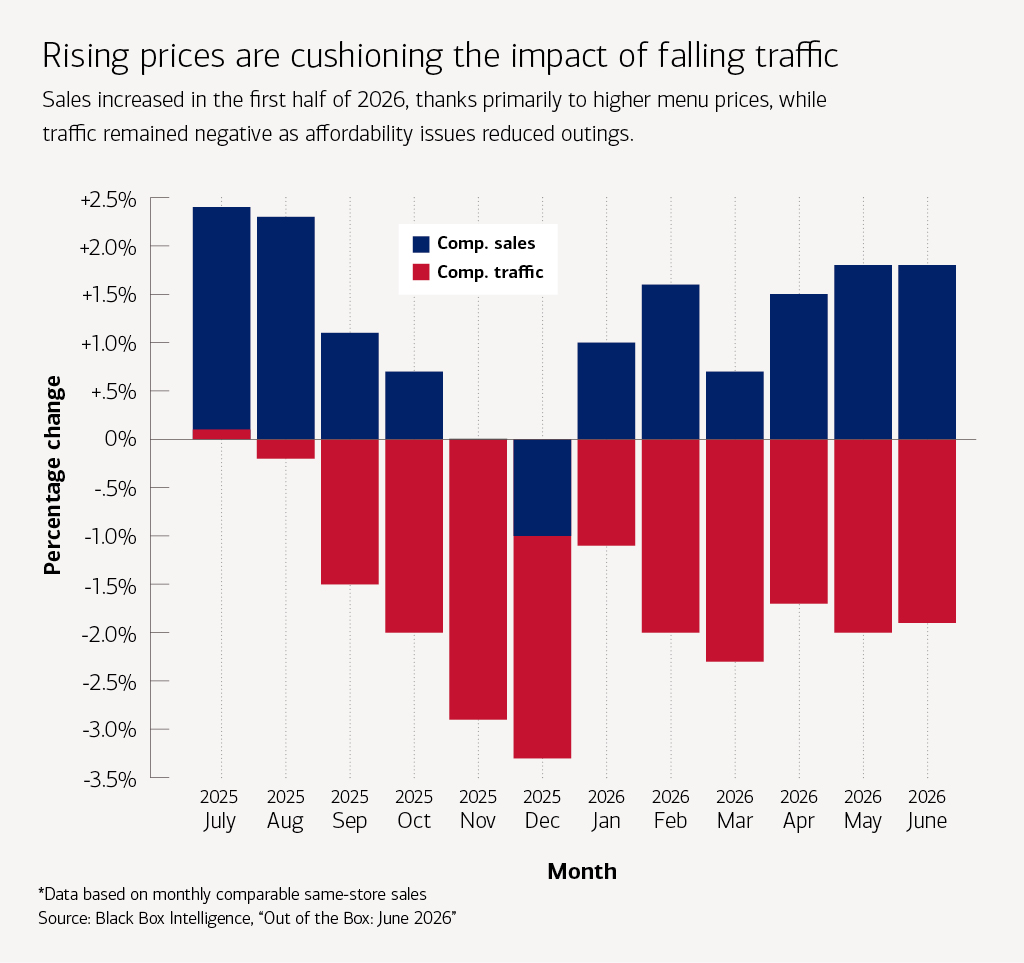
Restaurant operators are navigating a market that appears healthy at the topline but remains challenging at the unit level. Consumer appetite for dining out remains resilient despite ongoing household budget pressures. Overall sales continue to grow, although the climb is largely due to higher food prices rather than stronger traffic. At the same time, profitability remains under pressure as operators contend with higher supply chain and labor expenses, intensifying competition, and shifting consumer behavior that can influence traffic, menu mix and spending levels.
While overall demand remains strong, rising household expenses are leading many consumers to be more selective about where they dine out, how often they visit and what they order. As a result, operational efficiency and discipline are now paramount for operators competing on value while protecting margins. That can mean tighter labor scheduling and inventory controls or menu and footprint adjustments that can improve profitability.
“Sustained profitability has become the industry’s defining challenge … that is driving a much greater emphasis on consistent execution.”
“Sustained profitability has become the industry’s defining challenge,” says Cristin O’Hara, head of Bank of America Global Commercial Banking’s Restaurant Group. “Restaurant operators have always managed through change, but today’s environment leaves very little margin for error. That is driving a much greater emphasis on consistent execution across every aspect of the business.”
Industry trends and insights
Demand endures as consumer spending patterns change
Analyst projections call for restaurant industry sales to reach $1.54 trillion in 2026, representing baseline growth of 4.3%, a decline of 0.5 percentage points from the projection made at the start of the year. That forecast, however, partly reflects higher menu prices driven by increases in ingredient costs, wages and other operating expenses rather than stronger traffic. When adjusted for inflation, the industry is expected to grow a modest 0.8%, according to a July estimate by the National Restaurant Association. Still, demand has proved resilient, with most consumers continuing to prioritize restaurant dining. A majority (61%) say that restaurants remain an essential part of their lifestyle despite their tighter budgets.1,2
According to Bank of America Institute credit and debit card data, restaurant spending grew 3.3% year-over-year through July 2026. Despite concerns about affordability, the data showed that lower-income households’ restaurant spending increased 4.1%, more than for middle- or higher-income cohorts.3 Rather than pull back on dining out entirely, many consumers are responding by dining out less often, taking advantage of promotions and loyalty rewards, or adjusting their menu choices to manage spending. That can mean skipping appetizers, sharing entrees or even having drinks at home prior to going out.
Restaurant unit turnover was significant in the first half of 2026. There were 9,541 restaurant openings, with an estimated 61% by independent operators. Some 77% of openings were concentrated in the Sun Belt states of the Southwest, Southeast, and West.4 At the same time, there were 8,171 restaurant closings in the first half, including 4,253 chain outlets and 3,918 independent restaurants.5
O’Hara says that with the supply of dining options expanding faster than the number of consumers to fill them, unit growth is becoming a less reliable signal of valuation than in the past. As a result, investors are putting more weight on return on investment and unit level economics than on same-store sales trends.
Today’s operating environment is also being defined by sharp spending differences between socioeconomic cohorts. While unemployment remains relatively low, price hikes that outpace wage increases have led to a K-shaped economy in which higher-income households retain spending power, while less affluent consumers often feel the need to hunt for value.
External pressures add complexity
In addition to economic headwinds, restaurant operators have had to contend with unpredictable external challenges that can quickly alter consumer behavior, raise costs or disrupt operations. Spikes in gasoline prices, for example, have taken a toll on drive-in traffic, particularly on lower-income consumers. Shaky consumer confidence and growing use of popular weight loss drugs add another layer of uncertainty, influencing how often consumers choose to visit and how much they are willing to spend per outing.
Meanwhile, the recent cyclosporiasis outbreak revealed how disruptive food-borne illnesses can be, both to supply chains and consumer demand. Even a relatively short-lived interruption can have a significant impact on an industry built around consistent menus and tight margins, where operators may struggle to find alternative, affordable substitute ingredients or suppliers.
Taken together, these forces are introducing new vulnerabilities for restaurants already feeling the pressure of thin margins. Operators have limited control over these factors, but contingency planning such as identifying alternate suppliers and disciplined cost management can help them prepare to address and recover from temporary setbacks.
It’s a market share game
With so many consumers scrutinizing every discretionary dollar, brands must vie for a greater share of existing demand to find growth. “This is definitely more of a take-share environment,” says Christopher Holtz, a senior relationship manager with Global Commercial Banking at Bank of America. “It’s not a rising-tide-lifts-all-boats environment.”
Both individual brands and entire segments now compete on perceived value. That reality has been particularly challenging for quick service restaurants (QSRs). Aggressive menu price increases at some chains narrowed the price gap with fast casual, prompting some consumers to trade up for an experience they view as a better overall value.6
Meanwhile, casual dining operators are seeing some consumers move down the price chain in an effort to economize. At the same time, casual dining is the only sector where unit counts have declined and stayed lower, improving sales on a per-unit basis. As a result, fast casual’s sales growth has consistently outpaced that of quick service, casual dining and fine dining in recent years, according to BofA Global Research.7
Operators who have best managed three key challenges — pricing discipline, menu innovation and operating efficiencies — have been better positioned and able to lure or recapture value-conscious diners. Casual dining brands like Chili’s, Texas Roadhouse and Olive Garden, fast casuals like Chipotle and Cava, and QSR outlets like Chick-fil-A and Wingstop have generally outperformed on sales growth and operating performance.
“The strong get stronger, especially in periods of high inflation with a pinched consumer,” says Holtz. “Size brings efficiencies in marketing and pricing that can be used to gain share.”
Consumer preferences shift menu strategy
A national movement toward health consciousness is impacting what and how much consumers want to eat. The trend is driving demand for protein-rich menu items, leaner preparations and fiber-enhanced products.
In response, restaurants have been highlighting existing offerings, reformulating current items, or launching new ones to align menus with evolving nutritional priorities for more protein and low-carb/gluten-free options. Some have also started to include calorie counts and nutritional information to cater to consumers interested in making healthier food choices.
“People are still going out, but they’re eating less and prioritizing differently.”
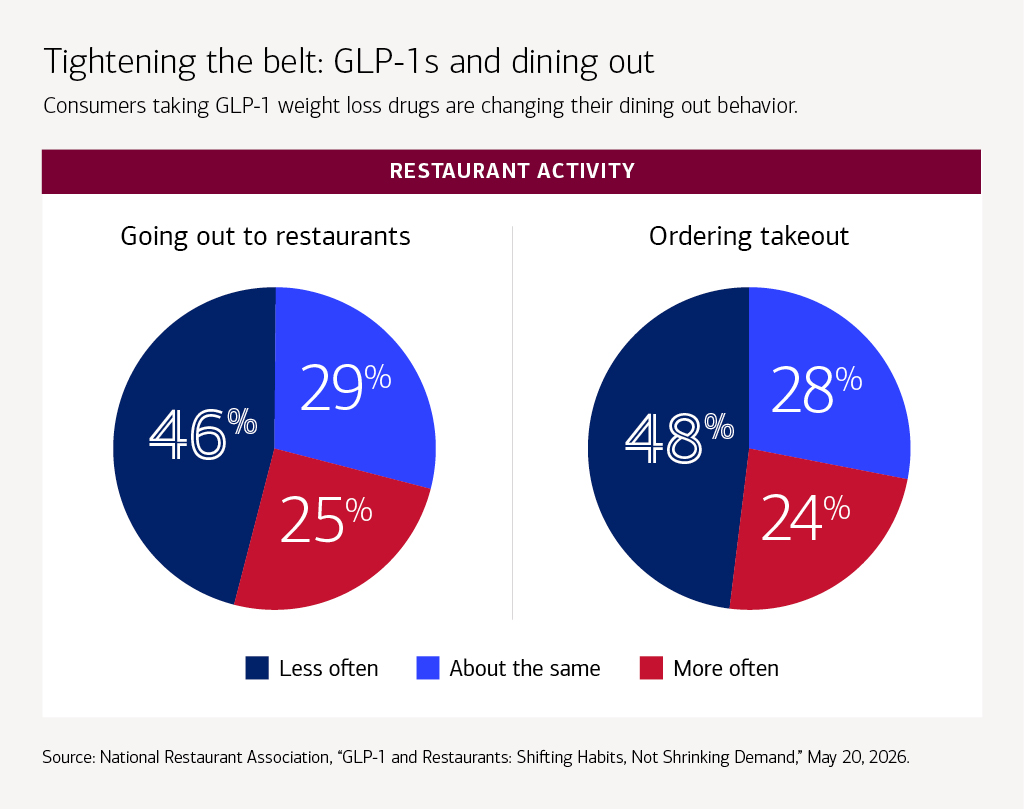
Customer menu choices have also been shifting toward smaller food and drink orders,8 a trend likely to continue as widespread use of GLP-1 medications influences consumer behavior.
Younger diners in particular prize ingredient transparency and minimally processed foods, says Aliya Willis, a senior relationship manager with Global Commercial Banking at Bank of America. “We’re seeing a lot of brands add protein to their menus or offer smaller meal sizes because people are eating less,” she says.
“People are still going out, but they’re eating less and prioritizing differently,” says Holtz, who points to some operators reducing portion sizes as exemplifying an effective response. “These trends are not going to kill the industry, but they are changing the choices operators need to make around portioning, menu architecture and value.”
Leveraging the beverage boom
Source: Consumer Edge, “Restaurant 2026 Mid-Year Outlook,” July 2026.
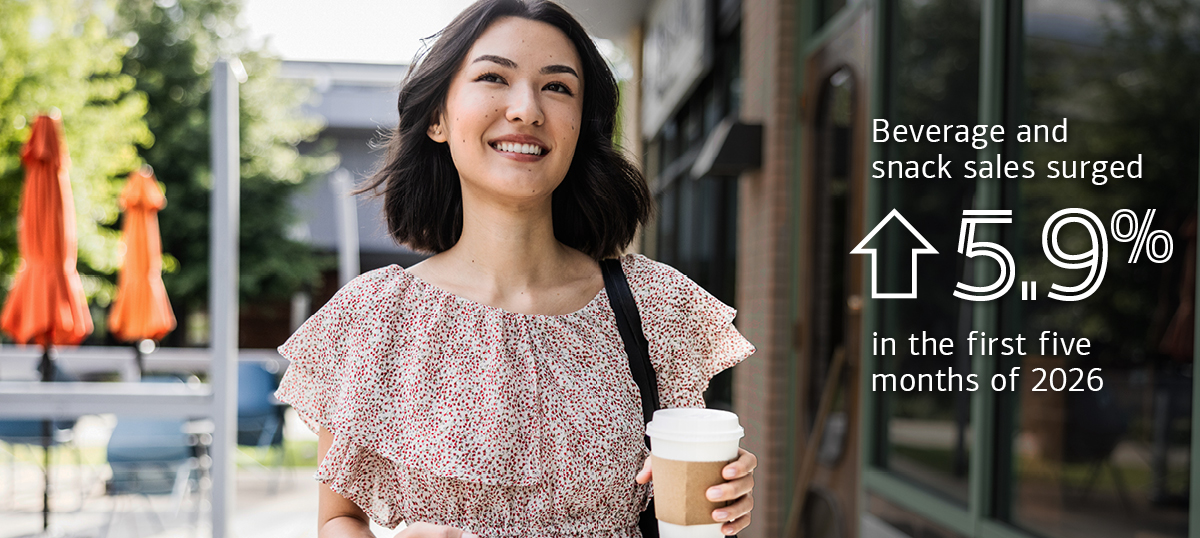
Once largely an add-on sale for restaurants, beverages have become a destination purchase, particularly for younger consumers who value customization, visual appeal and affordable small luxuries. For some consumers, iced coffee or specialized beverages like dirty sodas are an inexpensive indulgence that complements or occasionally substitutes for a meal.
Drive-through coffee brands like Dutch Bros and Arkansas-based startup 7 Brew, which has grown from just 38 stands in 2023 to more than 700 stores today, have expanded rapidly with their array of colorful “refreshers” and energy drinks. That success has spurred established operators to expand their drink offerings with options like freezes to capitalize on the growing beverage market.
“Operators are asking, ‘We have the space, we have the consumer — why would we let somebody else take this opportunity?’” says Valerie Sanger, a senior relationship manager with Global Commercial Banking at Bank of America. “They can increase sales of a high-margin item, and the new beverage offerings will also generate traffic.”
Technology shifts from cost control to improved profitability
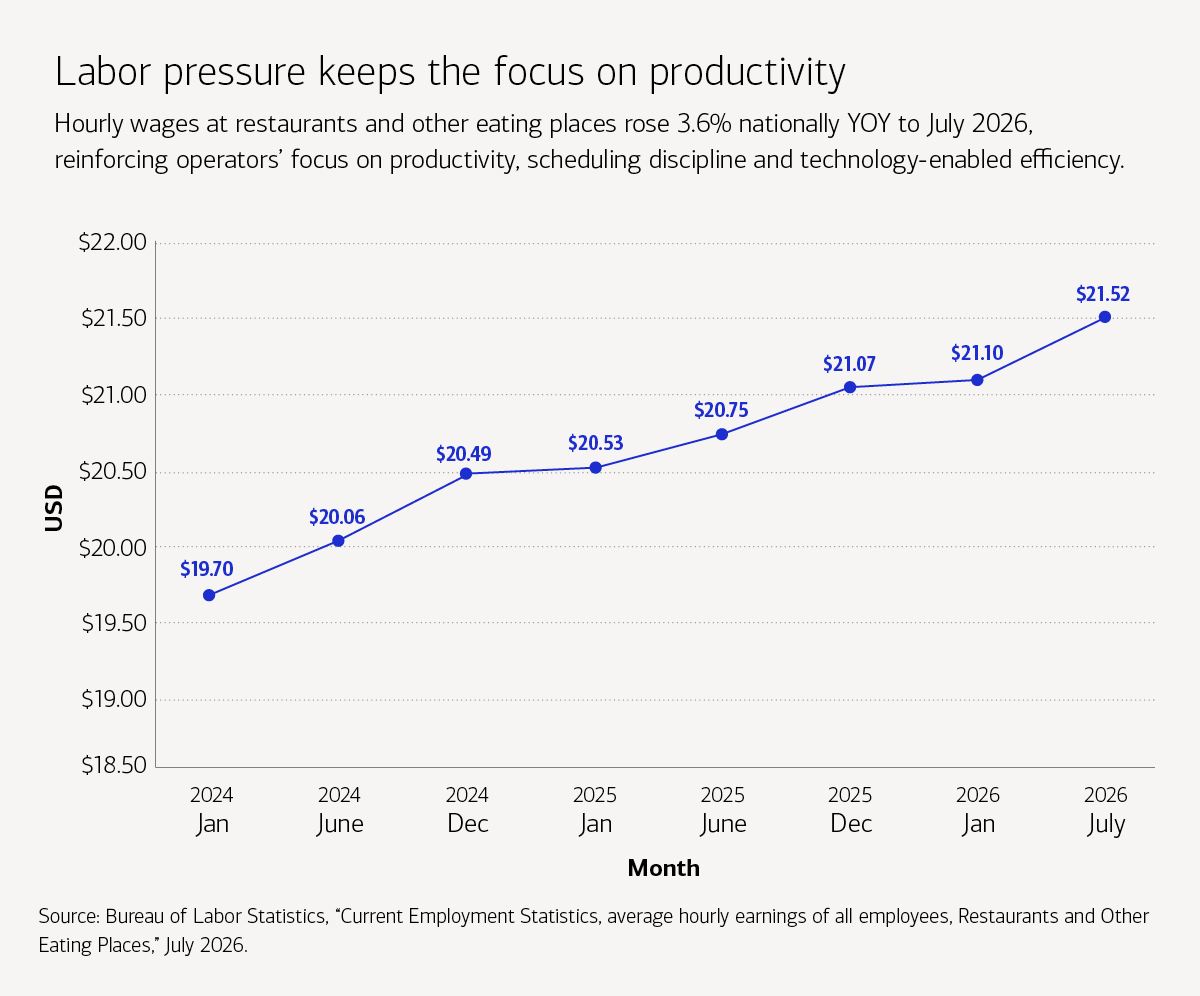
While staffing challenges have eased over the past year, operators continue to invest in automation to reduce labor costs — which rose 3.6% in the year ending July 2026 — and improve productivity.9
Many operators use kiosks to reduce front-end staffing needs, robotics to cut the number of workers performing repetitive food preparation tasks and integrated financial systems to streamline back-office processes and improve visibility. For more on managing staffing issues, see Bank of America’s report, How to attract and retain restaurant employees with benefits.
For operators with the capital and infrastructure to invest, AI-enabled tools are increasingly being used for tasks such as demand forecasting, inventory planning, labor scheduling, order taking, personalization and offer optimization.10
On the back end, investing in digitization and integrated systems that connect banking, payments, enterprise resource planning (ERP) and supplier management can help reduce administrative work, improve cash visibility and strengthen controls. In addition to helping operators identify and address inefficiencies, integration has become a key tool to prevent fraud. For a deeper look at how automation is reshaping restaurant operations, see Bank of America’s analysis of restaurant technology adoption, Lowering costs and improving customer satisfaction.
“Restaurants that don’t have integrated systems depend on the back office to manually and accurately post their receivables,” says Charlie Murphy, a senior treasury sales officer with Global Payment Solutions at Bank of America. “If you integrate bank information with your ERP system, it’s automated, and that visibility helps you manage fraud while streamlining the operations of the business.”
Effective operators can also use liquidity management to gain an edge in today’s high-cost environment, adds Murphy. He notes that strategically managing excess cash may generate returns that help offset expenses, support reinvestment or support broader financial goals. “When margins are tight,” he says, “picking up an extra day or two of float can make a meaningful difference.”
Capital markets remain selective
Stubbornly high interest rates and unattractive valuations caused a decline in restaurant IPO and M&A activity in 2025. Selected transactions continued to get done in 2026. “While some concepts target strong unit economics and clear growth, others are reorienting their customer experience to reverse a challenging post-COVID operating environment,” says John Dorazio, an investment banker with Global Corporate and Investment Banking at BofA Securities.
Brands able to demonstrate resilience, customer loyalty and a compelling value proposition can still command market attention by demonstrating consistent unit economics and disciplined execution, notes Dorazio. “Broadly, buyers are taking a cautious approach to investing in the restaurant sector, due in part to their concerns about the resilience of consumer spending,” he says.
A difficult IPO environment also tends to have a dampening effect on M&A transaction volume, as private equity firms are less inclined to invest when exit opportunities are uncertain. “For overall optimism to grow around the sector, broadly, I think you’ll have to see a little bit more clarity in the macro environment that the consumer will continue to spend strongly,” Dorazio says, adding, “but there will always be interest in category-defining concepts with outstanding unit economics and consistent growth.”
In the current high-interest rate environment, a corner of the capital markets that has gained traction in the restaurant sector is whole business securitization (WBS), a debt financing structure that allows franchisors to raise capital against recurring royalty and future revenue streams.11 WBS has been an increasingly common financing path for both public and private franchisors. “It allows franchisors to raise a lot more capital at attractive rates relative to traditional debt capital sources,” says Dorazio.
2027 Outlook
Heading into 2027, operators should prepare for a market that remains resilient, but uneven. Consumer demand is likely to remain highly segmented, making it increasingly important to understand which customer groups are driving growth and where pricing power remains strongest. At the same time, inflation, labor availability, food safety concerns and broader economic conditions will continue to create uncertainty. Operators that plan for multiple scenarios and/or tailor strategies to different customer segments, while maintaining flexibility in pricing, staffing and menu strategy, will be best positioned to navigate the year ahead.
A bifurcated consumer market
Generational spending differences are shaping demand. Last year, baby boomers were the only demographic to log increases in both average spending and transaction volume dining out.12 This year, Gen Z consumers — young people ages 14 to 29 — stand out as a notable exception to the K-shaped pattern, continuing to spend at higher levels and demonstrating the lowest savings-to-spending ratio of any generation.13
As Gen Z’s spending power increases, operators will likely see growing demand for experiences centered on convenience, customization, visual appeal, digital ordering and affordable indulgences. The opportunity is not simply to chase younger consumers, but to understand the occasions they value most. Operators should evaluate whether their menus, loyalty programs, mobile experiences and beverage offerings are positioned to capture this growing segment’s spending.
Riding the beverage boom
Beverages will continue to be an avenue of opportunity for restaurant operators, particularly as younger consumers increasingly embrace drinks as destination purchases. This demographic is 40% more likely than older consumers to consume beverages away from home, and 65% of their beverage occasions occur with food, which helps explain their venue choices, according to a survey by beverage firm Keurig Dr Pepper.14
“The younger demographics are really driving the beverage trend,” says Sanger. “They can get tea and coffee 10 different ways and they are willing to pay for it. It’s had a huge impact.”
Younger consumers tend to rotate through drinks rather than choose and stay with a specific beverage. This trend may create opportunities for operators whose beverage offerings align with consumer preferences for customization, novelty and convenience.
According to the survey, 71% of younger consumers expect both health and enjoyment in their beverage choices. The intersection of beverage innovation and wellness is another trend operators may want to monitor as consumer preferences continue to evolve. Examples emerging in the market include protein-rich coffees and smoothies, lower-sugar drinks or more naturally derived sweetening alternatives, and vitamin-enhanced options that appeal to consumers seeking both enjoyment and perceived health benefits.
The impact of GLP-1 drugs is just beginning to be felt
The prevalence of GLP-1 drugs is another variable to watch. Broader adoption, especially since the drugs are now covered for Medicare reimbursement, is likely to bring further changes in consumer preferences especially around portion size, menu mix and visit frequency. “GLP-1s are here to stay,” says O’Hara. “Whether that leads to smaller, more frequent meals or fewer meals out altogether has yet to play out in terms of traffic.”
Some industry observers believe that restaurants may feel only limited impact from GLP-1 drugs because dining out is often a social occasion rather than simply functional. Nonetheless, GLP-1 adoption will sharpen consumer focus on value, portion size and wellness. Some analysts foresee a potential negative impact on restaurant revenue. FTI Consulting has estimated that by 2030, GLP-1 adoption could be responsible for 3 billion fewer restaurant-equivalent meals per year, with QSRs likely to be hardest hit.15 As adoption grows, operators may need to evaluate whether evolving consumer preferences warrant changes to menu architecture, portion strategy or product mix by experimenting with smaller portions, healthier sides and greater menu customization.
Adapting the operating model
The pressure of ever-tightening margins is likely to continue to push operators to rethink restaurant footprints and operating models in search of greater efficiency and profitability. Identifying ways to adapt real estate, instill operational discipline and improve cost control will remain critical. Already, some operators have been reassessing restaurant footprints, formats and off-premises capacity to better align real estate costs with how customers order, pick up and consume meals. More are likely to explore ways to reduce the amount of expensive dining space while preserving the capacity to serve takeout, delivery and drive-thru customers, who now account for 75% of total restaurant traffic.16
Bringing two concepts under one roof is another path toward higher profitability that more owners may pursue in the coming year. Two-in-one concepts can boost traffic by bringing menu offerings with breakfast and afternoon/evening appeal under one roof or introducing a beverage-only brand concept within a QSR location.
“Restaurant owners are always looking at how to maximize the volume that comes out of the smallest footprint possible,” says Holtz, who adds that scale helps. “Entities that have the cash flow can either take out dining space or create a more efficient kitchen, or both.”
The flexibility mandate
While much about the future remains murky, what is clear is that the impact of forces reshaping the industry will not be felt evenly across brands, segments and consumer groups. That makes speed, discipline and adaptability critical competitive advantages.
From a menu standpoint, this may mean greater emphasis on tools like using limited-time offers to respond to changing consumer preferences and keep menus fresh. In back offices, it translates to leaning into technology-fueled forecasting that can help restaurants staff and manage inventory more efficiently. The goal is not to simply cut costs but to strengthen the ability to deploy, and redeploy, resources effectively as consumer behavior and economic conditions evolve.
“Restaurant operators can’t determine where the economy is headed, but they can work on how well prepared they are to navigate it,” says Holtz, who points to employee engagement, operational discipline and innovation as areas of focus. “Operators that can be thoughtful and proactive in leveraging new technologies and finding ways to deliver value, convenience and experience will be best positioned for whatever lies ahead.”
FAQs
Contributors:

Cristin O’Hara
Head of the Restaurant Group, Global Commercial Banking | Bank of America

John Dorazio
Investment banker, Global Corporate and Investment Banking | BofA Securities

Charlie Murphy
Senior treasury sales officer, Global Payment Solutions | Bank of America

Christopher Holtz
Senior relationship manager, Global Commercial Banking | Bank of America

Valerie Sanger
Senior relationship manager, Global Commercial Banking | Bank of America

Aliya Willis
Senior relationship manager, Global Commercial Banking | Bank of America
1 National Restaurant Association, “Report: Sales to hit $1.55T in 2026 despite challenging business environment,” Feb. 13, 2026.
2 National Restaurant Association, “Restaurants remain resilient despite challenging business conditions,” July 22, 2026.
3 Bank of America Institute, “Restaurants: What’s cooking in consumer spending?” Aug. 24, 2026.
4 Restaurant News, “New Restaurant Development Remained Concentrated in Sun Belt and Western Markets During First Half of 2026,” July 1, 2026.
5 RestaurantData.com, “First-Half 2026 U.S. & Canada Restaurant Closure Report,” July 2026.
6 Clearcogs, “Restaurant Demand at the Midpoint: The First Half of 2026 in Review, and What to Watch in the Second Half,” July 2, 2026.
7 BofA Global Research, “Fast Casual: After a watershed 2025, revisiting segment and company views,” July 1, 2026.
8 National Restaurant Association, “GLP-1 and Restaurants: Shifting Habits, Not Shrinking Demand,” May 20, 2026.
9 Bureau of Labor Statistics, “Current Employment Statistics, average hourly earnings of all employees, Restaurants and Other Eating Places,” July 2026.
10 Bank of America, “Lowering costs and improving customer satisfaction,” 2026.
11 Restaurant Business, “What on earth is a whole business securitization and why is it so popular?” Sept. 19, 2024.
12 Bank of America Institute, “Taste test: Where consumers are dining out,” Feb. 12, 2026.
13 Bank of America Institute, “The Gen Z Reality Check,” Aug. 4, 2026.
14 Keurig Dr Pepper, “State of the Beverage Report,” 2026.
15 FTI Consulting, “GLP-1 Drugs Are Rewriting the Rules of Food and Beverage,” July 2026.
16 National Restaurant Association, “From Trend to Transformation,” April 16, 2025.